R0263: PASS
Rule: When size of the move from the open to 09:30 (either direction) ≤ 0.11% (≈29 pts at 25,000) AND size of the opening gap ≤ 0.11% (≈28 pts at 25,000) AND it is not expiry day at 09:30
Target: price never trades back to the open after 09:30 · Decision time: 09:30 IST (uses bars up to 09:30 only) · Method: subgroup · Family: level / structure
Verdict criteria
- ✔ Out-of-sample lift in the same direction as train
- ✔ OOS Wilson 95% CI excludes the OOS base rate
- ✔ OOS BH q ≤ 0.05 across all candidates tested OOS AND within its target family
- ✔ Train BH q ≤ 0.05 (across all hypotheses searched)
- ✔ Stable by year (same direction in ≥80% of years with ≥10 days, incl. every OOS year with ≥10)
- ✔ OOS matched-random placebo p ≤ 0.05
- ✔ OOS sample ≥ 20 days
Train p 5.5e-07; train BH q 5.1e-05; train Holm 1.000 (corrections over all 9,242,869 hypotheses); whole-pipeline shuffled-label placebo family-wise p 0.277 (100 permutations). Extra conditions beat the best single condition OOS: False.
By year
| year | rule days | hit | base (all days) | lift |
|---|---|---|---|---|
| 2022 | 6 | 0% | 28% | 0.00 |
| 2023 | 19 | 0% | 26% | 0.00 |
| 2024 | 25 | 0% | 25% | 0.00 |
| 2025 (OOS) | 23 | 17% | 35% | 0.50 |
| 2026 (OOS) | 16 | 12% | 32% | 0.40 |
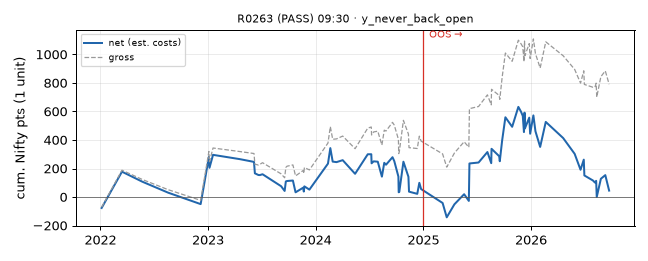
Spot-points backtest (estimated costs)
enter at 09:30 price against the move direction; stop 0.4% of entry; exit at close. Costs: Nifty futures round-trip model from nifty-setups-backtest/src/costs.py (brokerage, exchange, SEBI, stamp, GST, STT by date: 0.0125% → 0.02% from Oct-2024 → 0.05% from Apr-2026) + 0.5 pt slippage per side; spot used as a futures proxy (basis ignored); stop-first on ambiguous bars.
| window | trades | win rate | avg net pts | avg gross pts | total net | max DD pts | PF |
|---|---|---|---|---|---|---|---|
| train 2022–24 (in-sample) | 50 | 42% | +1.1 | +7.8 | +55.9 | +320.9 | +1.0 |
| OOS 2025–26 | 39 | 44% | -0.3 | +10.2 | -10.7 | +631.9 | +1.0 |
trades.csv · Generated 2026-10-10 00:44 IST.